News & Tech Tips

Working teens can maximize the power of tax‑deferred — or tax-free — compounding with an IRA

Retirement is far from most teenagers’ minds when they get their first jobs. Most young people are more interested in spending their earnings or saving for a shorter-term goal. But those early earnings create a significant financial opportunity: decades of potential tax-advantaged growth. Even modest contributions to an IRA now can substantially multiply over time. Moreover, a retirement account can help teens get into the habit of saving.


Traditional vs. Roth IRAs


Working teens can opt for a traditional IRA or a Roth IRA. Both offer the power of tax-advantaged compounding. For example, just $2,000 contributed to an IRA earning 5% annually will grow to nearly $23,000 50 years later. But there are important tax differences between the two types of IRAs:

Traditional IRA. Contributions to a traditional IRA will usually be deductible for teens. The deduction may be phased out if a taxpayer’s income exceeds certain amounts and he or she (or his or her spouse) participates in a qualified retirement plan, such as a 401(k). But teenagers generally won’t be affected by these limitations.

On the downside, traditional IRA withdrawals are generally taxable. In addition, a penalty applies if funds are withdrawn before age 59½ — unless an exception is available — and a larger penalty applies if required minimum distributions (RMDs) aren’t taken beginning at the age required (75 for today’s teens if future legislation doesn’t increase it).

Roth IRA. Roth IRA contributions are never deductible. But withdrawals — including earnings — are tax free as long as the account owner is age 59½ or older and the account has been open at least five years. In addition, contributions can be withdrawn at any time tax- and penalty-free. There also aren’t RMDs for Roth IRAs during the original owner’s lifetime.

To contribute to either a traditional or a Roth IRA, a teen must have taxable compensation, such as wages or net earnings from self-employment. For 2026, the annual contribution limit for IRAs is the lesser of taxable compensation or $7,500. This is on a combined basis for both types of IRAs.

Typically, a parent or other adult opens a custodial IRA for a minor. The child takes control when he or she reaches the age specified under applicable state law and the account arrangement.


Roth IRA advantages


Because many working teenagers have little or no taxable income after their standard deduction is applied, a deduction for a traditional IRA contribution often provides little immediate tax benefit. As a result, a Roth IRA can be the more attractive option.

Consider Abigail, 16, who started her first part-time job at a local cafe and expects to earn $7,500 in 2026. Her parents want to help her develop a habit of saving. They set up a Roth IRA for her because her account should have many decades to grow and qualified distributions will be tax-free.

Abigail’s income is low enough that she likely will owe no federal income tax, so a current deduction for traditional IRA contributions will probably offer little, if any, benefit. Even if she does owe some tax, she’ll be in the lowest bracket (10%). The potential for tax-free qualified distributions in the future is, therefore, more valuable than a deduction for a traditional IRA contribution now.

Abigail doesn’t even have to use all of her own earnings to make the contribution. If she wants to contribute only $1,500 of her earnings, her parents, grandparents or others could give her $6,000 so she can contribute the full $7,500 and still have $6,000 available for spending or a shorter-term savings goal. But her family should consider any gift-tax reporting or college financial-aid implications before using this approach.


An IRA alternative


Section 530A (Trump) accounts provide another tax-advantaged savings opportunity for teens. They’re similar to an IRA, but contributions don’t require the child to have earned income. (The $1,000 federal contribution you probably have heard about is limited to qualifying children born from 2025 through 2028, so today’s teens aren’t eligible.)

Even though, like a Roth IRA, contributions aren’t deductible, the portion of distributions attributable to growth will be taxable. Also, depending on how much a working teen earns during the year, he or she may be able to contribute more to a traditional or Roth IRA. Annual contributions to a 530A account are generally limited to $5,000, though some special contributions don’t count toward that limit.

530A accounts also generally prohibit distributions and restrict investments during the growth period (until the year the child turns age 18). So a traditional or Roth IRA may offer a working teen more flexibility.

If a family can afford to contribute to both an IRA and a 530A account for a teen who’s eligible for both, that may be an even more powerful savings opportunity, with potentially a combined contribution of as much as $12,500 for 2026. But because 530A accounts were only recently enacted, IRS and Treasury guidance is still developing. Future guidance could affect the rules.


Employing your children


If your teen doesn’t currently have earned income but you own a business, consider hiring him or her. Employing your child can provide the earned income needed for an IRA contribution, and you can deduct his or her pay as a business expense. The child should be old enough to handle the assigned responsibilities, perform real work and receive reasonable compensation. An excessive pay rate for routine duties could draw IRS scrutiny. Keep records of the child’s duties, hours and pay.

If the business is a sole proprietorship or a partnership in which each partner is a parent of the child, wages paid to a child under age 18 aren’t subject to Social Security and Medicare taxes. Wages paid to a child under age 21 aren’t subject to federal unemployment tax. But the wages are subject to federal income tax withholding regardless of age.

If the business is a corporation, or a partnership in which not every partner is a parent of the child, the wages are subject to federal income tax withholding and Social Security, Medicare and federal unemployment taxes regardless of the child’s age. That’s true even if a parent controls the corporation.


Put early earnings to work


For a working teen, an IRA can provide an early start on decades of tax-advantaged saving. 2026 contributions can be made until April 15, 2027, but the income to support them must be earned by December 31, 2026.

Whether a traditional or Roth IRA is better — and how a 530A account might fit in — depends on a variety of factors. We can help you determine what fits your family’s circumstances and put those early earnings to work for the future.

How do donations impact your tax deductions

Have you already made contributions to charity this year? Are you considering making more between now and year end? If so, it’s important to be familiar with the tax rules for different types of donations so you can maximize your tax benefit — or at least avoid finding out at tax filing time that your charitable deductions are smaller than you expected.

For example, be aware that a new limit goes into effect this year: a 0.5% floor on the charitable deduction for itemizers. This generally means that only charitable donations in excess of 0.5% of your adjusted gross income (AGI) will be deductible if you itemize deductions. So, if your AGI is $100,000, your first $500 of charitable donations for the year won’t be deductible.

Let’s take a look at some of the other significant rules, limits and changes affecting different types of donations.

Giving cash

When you make a cash or cash-equivalent contribution to a qualified charitable organization, if you don’t itemize deductions, you can claim the new charitable deduction for nonitemizers of up to $1,000 ($2,000 for married couples filing jointly). Only cash donations qualify.

If you do itemize deductions, you can generally deduct the full amount of cash contributions once you’ve surpassed the new 0.5% floor. But, your annual deduction is generally limited to 60% of your AGI. Any excess may be carried forward for up to five years.

Be aware that the IRS imposes strict recordkeeping rules for cash contributions. For instance, for cash donations of $250 or more, you must obtain a contemporaneous written acknowledgment from the charity before filing your income tax return.

Donating property

Several special rules apply to charitable gifts of property. For starters, property donations are subject to lower annual deduction limits (which we’ll detail shortly).

On the plus side, there’s a big tax break if you donate certain appreciated property you’ve held longer than one year that would have qualified for long-term capital gains rates had you sold it instead of donating it. In this case, you can deduct the property’s current fair market value. Thus, any appreciation in value while you owned the property will be untaxed. Examples of eligible property include publicly traded securities and mutual funds. However, your annual deduction for such donations is typically limited to 30% of AGI.

For tangible property, how the charity uses the property may affect the amount of your deduction. For example, if you donate a car, unless it’s being used by the charity to further its charitable mission (such as a social services charity using a van to deliver meals to the elderly), you generally may deduct only the amount the charity receives when it sells the vehicle. But a 50% of AGI limit typically applies to deductions for donations where you can’t deduct the fair market value, rather than the 30% limit.

These are just a few examples of rules that apply to deductions for property donations. Contact us to find out the rules for specific property you’re considering giving to charity.

Making quid pro quo contributions

Generally, if you receive a benefit in return for making a donation, your deduction amount is reduced. For such a “quid pro quo contribution,” the charity must provide a good-faith estimate of the goods and services you received. You can deduct the difference between the amount you donated and the value of the benefit you received — nothing more.

For example, let’s say you attend a fundraising dinner cruise costing $300. If the charity values the meal and boat ride at $100 per person, your deduction is limited to $200. However, most low-cost items and nominal gifts, like coffee mugs or pens featuring the charity’s logo, don’t have to be subtracted from your deduction.

Volunteering

You can’t deduct the value of the time you spend helping a charity. But you can write off related out-of-pocket expenses, such as supplies and mileage, if you itemize deductions. The deductible mileage rate for charitable miles driven is 14 cents per mile.

Travel and lodging expenses can qualify, such as if you attend a convention as a delegate for the charity. However, travel expenses can’t be deducted if the trip is merely a disguised vacation.

Achieving your goals

If you itemize deductions, charitable donations can be a powerful tax-saving tool. But, as you can see, there’s much to consider as you plan your giving for the rest of the year. We can answer your questions and help you create a charitable giving strategy for the remainder of 2026 that aligns with your philanthropic and tax goals.

Before you spend lottery, gambling or other winnings, understand the tax rules

It’s easy to focus on the excitement of a big win. But federal tax law generally treats lottery prizes, gambling winnings and other awards as taxable income. Knowing the basic rules can help you avoid surprises when you file your 2026 return next year.

Lottery prizes

Of course, the chances of winning big in the lottery are slim. But many people win smaller, yet not insignificant, amounts that can increase their tax liability — in some cases, substantially.
Lottery winnings are taxable for federal purposes. This is the case for both cash prizes and the fair market value of noncash prizes, such as a car or vacation. Depending on the amount won and your other income, the winnings could push you into a federal tax bracket as high as 37%. Your winnings may also be subject to state income tax.

You must report lottery winnings as income in the year, or years, you actually receive them. In the case of noncash prizes, this would be the year you receive the prize. With cash, if you take the winnings in annual installments, you report each year’s installment as income for that year.

Gambling winnings

For federal tax purposes, it doesn’t matter if you win at the casino, a bingo hall or elsewhere. You must report 100% of your gambling winnings as taxable income. They’re reported on an “Other income” line of your 1040 tax return. To measure your winnings on a particular wager, use the net gain. For example, if a $50 bet at the racetrack turns into a $150 win, you’ve won $100, not $150.

You must separately keep track of losses. They may be deductible, but only if you itemize deductions. Therefore, if you take the standard deduction, you can’t deduct gambling losses.

In addition, you can deduct only 90% of gambling losses, and only up to the amount of gambling winnings. So if your losses exceed your winnings, you might be able use losses to “wipe out” gambling income — but you can’t offset other income with the losses.

Maintain good records of your losses during the year. Keep a detailed diary in which you note the date, place, amount and type of loss, as well as the name of anyone who was with you. Save all documentation, such as checks or credit slips.

Note: Different rules apply to people who qualify as professional gamblers.

Withholding and estimated tax payments

If you win more than $5,000 in the lottery or certain types of gambling, 24% must be withheld for federal tax purposes. You’ll receive a Form W-2G from the payer (lottery agency, casino, etc.) showing the amount paid to you and the federal tax withheld. (The payer also sends this information to the IRS.) If state tax is withheld, that amount may also be shown on Form W-2G.

Because your federal tax rate can be up to 37%, which is well above the 24% withheld, the withholding may not be enough to cover your federal tax bill. Therefore, you may have to make estimated tax payments to cover the rest of the liability — and you might be assessed a penalty if you fail to do so.

Have you won big?

Lottery, gambling or other winnings can increase income taxes and create estimated tax obligations. (There might also be state and local tax consequences.) If the winnings are large enough, you may need to revisit your wealth management strategy and revise your estate plan.

Please contact us if have questions. We’ll help you understand the tax impact and meet your tax obligations.

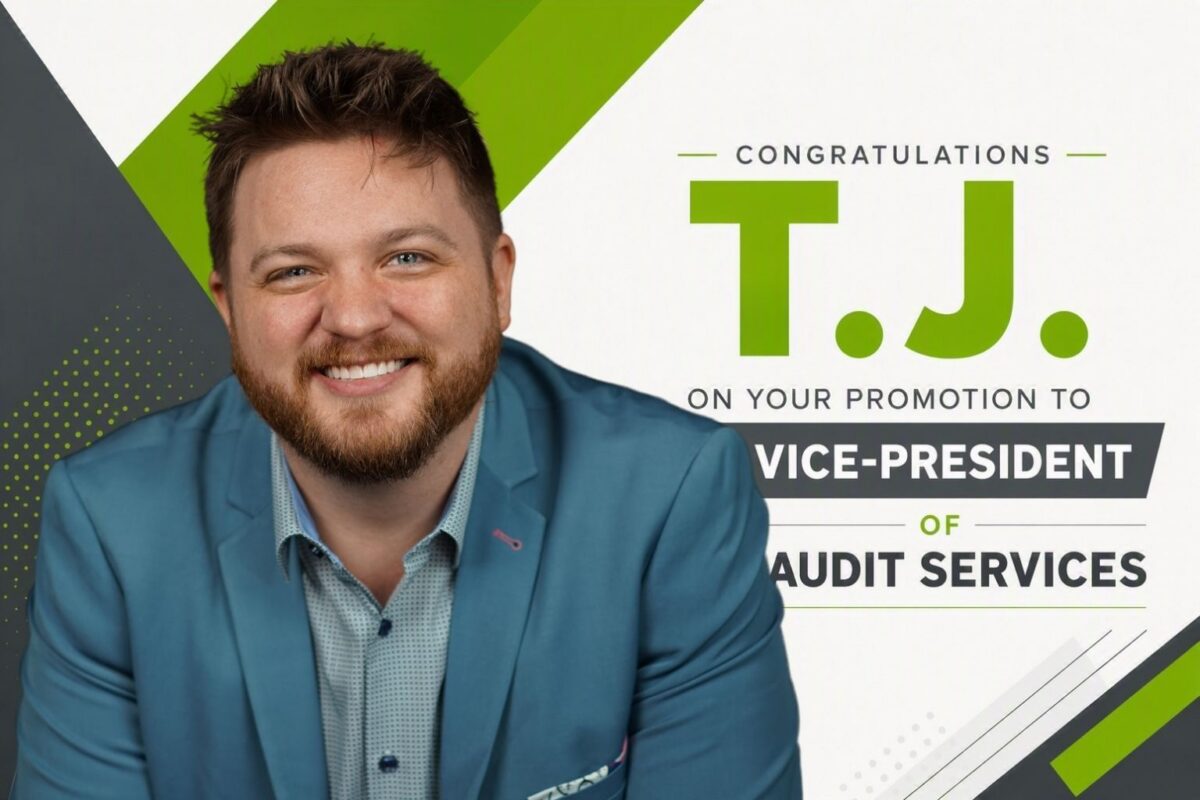
Whalen CPAs Announces T.J. Lowry as Vice President of Audit Services

Whalen CPAs is proud to announce that T.J. Lowry has been promoted to Vice President of Audit Services and named the firm’s newest Partner.

For T.J., becoming a partner is more than a professional milestone. It is a responsibility – to clients, to the team, and to the long-term future of the firm.

“In my youth, becoming partner was about the achievement,” T.J. shared. “Today, it’s about service and having an impact beyond the financial statements.”

That sense of responsibility has shaped much of T.J.’s career. Inspired by his father, a CPA, T.J. knew from a young age that he wanted to follow in his footsteps. Over time, that early admiration grew into something deeper: a desire to use the profession to help people make sense of complex issues, make better decisions, and move forward with confidence.

To T.J., strong audit work begins with getting the fundamentals right: planning, organization, communication, and technical rigor. But it cannot stop there. An audit team earns trust by telling the truth clearly, being willing to have difficult conversations, and helping clients understand not only what changed, but what those changes may mean for the organization they are trying to build.

“A good CPA gets the work right,” T.J. said. “A great advisor helps clients understand what the work means for where they are going.”

In his work with audit clients, T.J. values the opportunity to look beneath the surface, understand an organization’s goals, and identify where operations, risks, reporting, or processes may be out of alignment. He believes clients are served best by advisors who care deeply, communicate plainly, and are willing to bring an honest perspective to the table.

As a VP, T.J. is excited to continue strengthening Whalen’s audit practice around quality, consistency, client service, and team development. He sees the profession moving beyond traditional compliance and into deeper strategic guidance, where sound judgment, relationships, and clear communication matter more than ever.

When asked what he hopes clients experience when they work with Whalen, T.J. described a team that is organized, technically strong, easy to communicate with, and willing to have difficult conversations when needed. In his view, being in a client’s corner does not mean avoiding hard truths. It means earning enough trust to say what needs to be said, with clarity and care.

T.J. also sees this next chapter as an opportunity to help preserve and strengthen the culture that has meant so much to him. Whalen’s core values – Start with Heart, Stand Up Straight, and Aim Higher – are not just words to him. They are a practical standard for how the firm serves clients, develops people, and makes decisions.

T.J. shared. “The legacy I care about is helping steward the values that made Whalen worth joining in the first place, and helping foster them for future generations.”

Please join us in congratulating T.J. on this well-deserved promotion and exciting new chapter.

When the sale of an appreciated home triggers taxes — and when it doesn’t

Home values have risen significantly in many areas of the country over the last several years, leaving some homeowners with substantial gains when they sell. Of course a large profit is generally a good thing. But, depending on the amount of your gain, how long you’ve owned and resided in the home, and your income level, a sale may trigger capital gains tax and, in some cases, the net investment income tax (NIIT).

Save tax with the gain exclusion

If you’re selling your principal residence and meet certain requirements, you can exclude from tax up to $250,000 of gain ($500,000 for married couples filing jointly).

To qualify for the exclusion, you must:

  1. Have owned the property for at least two years during the five-year period ending on the sale date.
  2. Have used the property as a principal residence for at least two years during the five-year period. (Periods of ownership and use don’t need to overlap.)

In addition, you can’t use the exclusion more than once every two years.

Be aware of ineligible gain

What if you have more profit than your gain exclusion? Any gain in excess of the exclusion generally will be taxed at your long-term capital gains rate (typically 15% or 20%), as long as you owned the home for more than one year. If you didn’t, the gain will be considered short-term and subject to your marginal ordinary-income rate (usually 22% to 37%).

If you’re selling a second home (such as a vacation home), it isn’t eligible for the gain exclusion and the entire gain generally will be subject to capital gains tax. But if the home qualifies as a rental property, it can be considered a business asset. In that case, you may be able to defer tax through an installment sale or a Section 1031 like-kind exchange.

Watch out for the NIIT

When does the NIIT apply to a home sale? If you sell your principal residence and qualify for the gain exclusion, the excluded gain isn’t subject to the 3.8% NIIT.

However, gain that exceeds the exclusion is subject to the NIIT if your modified adjusted gross income (MAGI) is over a certain amount. Gain from the sale of a vacation home or other second residence, which doesn’t qualify for the exclusion, may also be subject to the NIIT.

The NIIT applies only if your MAGI exceeds $200,000 ($250,000 for joint filers or $125,000 for married taxpayers filing separately). If your MAGI is above the applicable threshold, additional factors will affect your NIIT liability. Be aware that the NIIT kicks in before the top long-term and ordinary-income rates apply.

Keep track of your basis

Gain on your home is calculated by subtracting your tax basis in the home from the sale price. Your basis generally includes what you paid for the home plus major improvements you made to it.

To support an accurate basis, be sure to maintain complete records, including information about your original cost and subsequent improvements (such as a kitchen remodel or a new roof). But basis-increasing improvements don’t include maintenance and repairs (such as painting your kitchen or fixing a leak in your roof). Also, you must reduce your basis by any casualty losses or depreciation claimed for business use (such as if a portion of your home was rented out or you claimed the home office deduction).

If your basis is more than what you sell your home for, your loss generally won’t be deductible. But if a portion of your home was rented out or used exclusively for business, the loss attributable to that part may be deductible.

Plan for the tax impact

A home sale can be tax-free or create a sizable tax liability — or result in a tax bill between those extremes. If you’re thinking about selling your home, it’s important to know the potential tax impact. Contact us before putting your home on the market so we can help you estimate the tax impact and discuss possible planning opportunities.